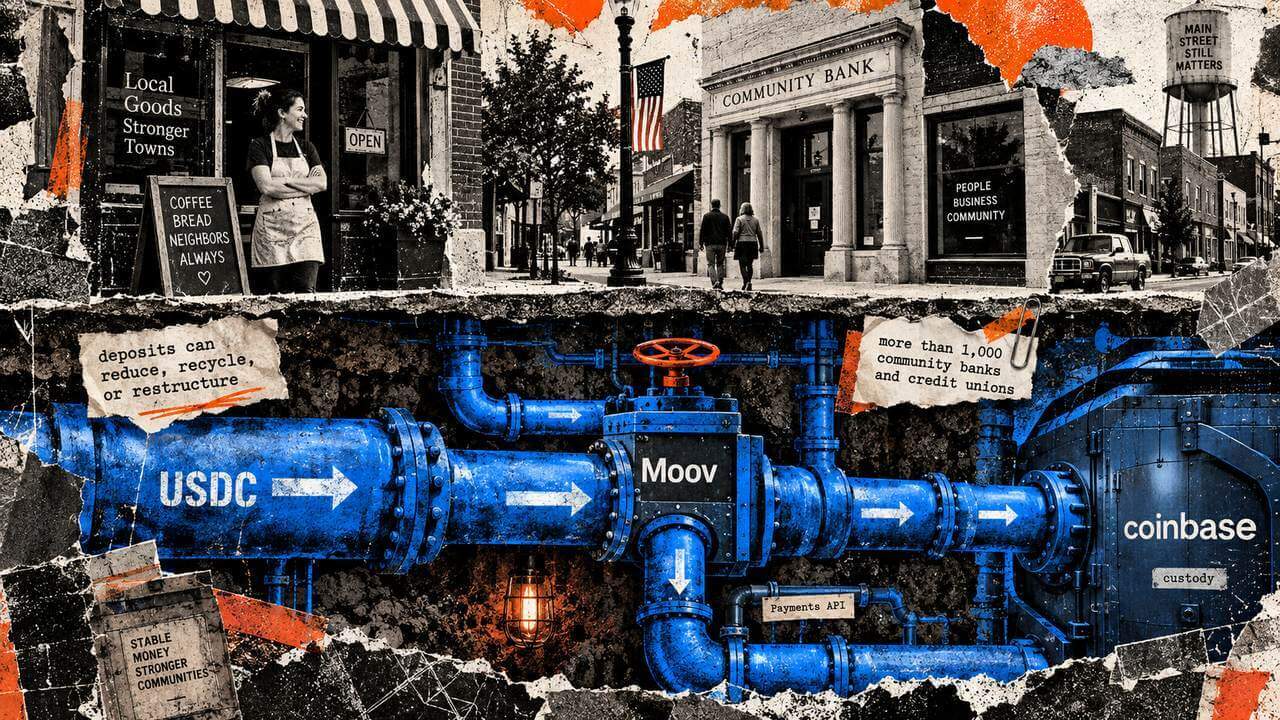
Coinbase’s new stablecoin bridge provides US community banks with the necessary backend infrastructure to facilitate digital asset transactions without the need for proprietary blockchain development. By supplying the underlying framework for data, settlement, and compliance, Coinbase allows these smaller institutions to retain their customer-facing interfaces while leveraging the efficiency of blockchain-based rails. This 'white-label' approach ensures that regional banks can offer 24/7 settlement capabilities and cross-border payments using regulated stablecoins like USDC.
The timing of this rollout in early 2026 follows a period of increased regulatory clarity regarding bank-issued and bank-facilitated stablecoins in the United States. For community banks, this bridge solves the technical hurdles of maintaining liquidity and meeting strict anti-money laundering (AML) requirements, as Coinbase integrates these features directly into the settlement layer. This shift allows local banks to mitigate the risk of deposits fleeing to larger crypto-native platforms or mega-banks.
From a market perspective, this move significantly expands the utility and velocity of stablecoins within the traditional financial system. Rather than forcing users to move funds to an exchange, Coinbase is essentially embedding the exchange’s efficiency within the traditional banking app. This trend is likely to drive higher transaction volumes for USD-pegged assets and increase the total value locked (TVL) in institutional-grade digital wallets.
Investors and bank customers should watch for which specific regional banking networks adopt this technology first, as this will determine the reach of Coinbase's infrastructure. Additionally, the undisclosed pricing and data-sharing terms between Coinbase and these banks will be critical in determining which party captures the most value from these new transaction fees. As the bridge scales, it could present a formidable challenge to legacy payment processors like SWIFT.